Semiconductors become an explicit industrial-policy priority
By Nathan Benaich and Ian Hogarth · 2022 report
The 2022 report examined government efforts to strengthen domestic chip capacity. Funding commitments could influence investment, but factories, equipment, and skilled workers took time to assemble. The strategic importance of chips did not make the supply chain easy to relocate.
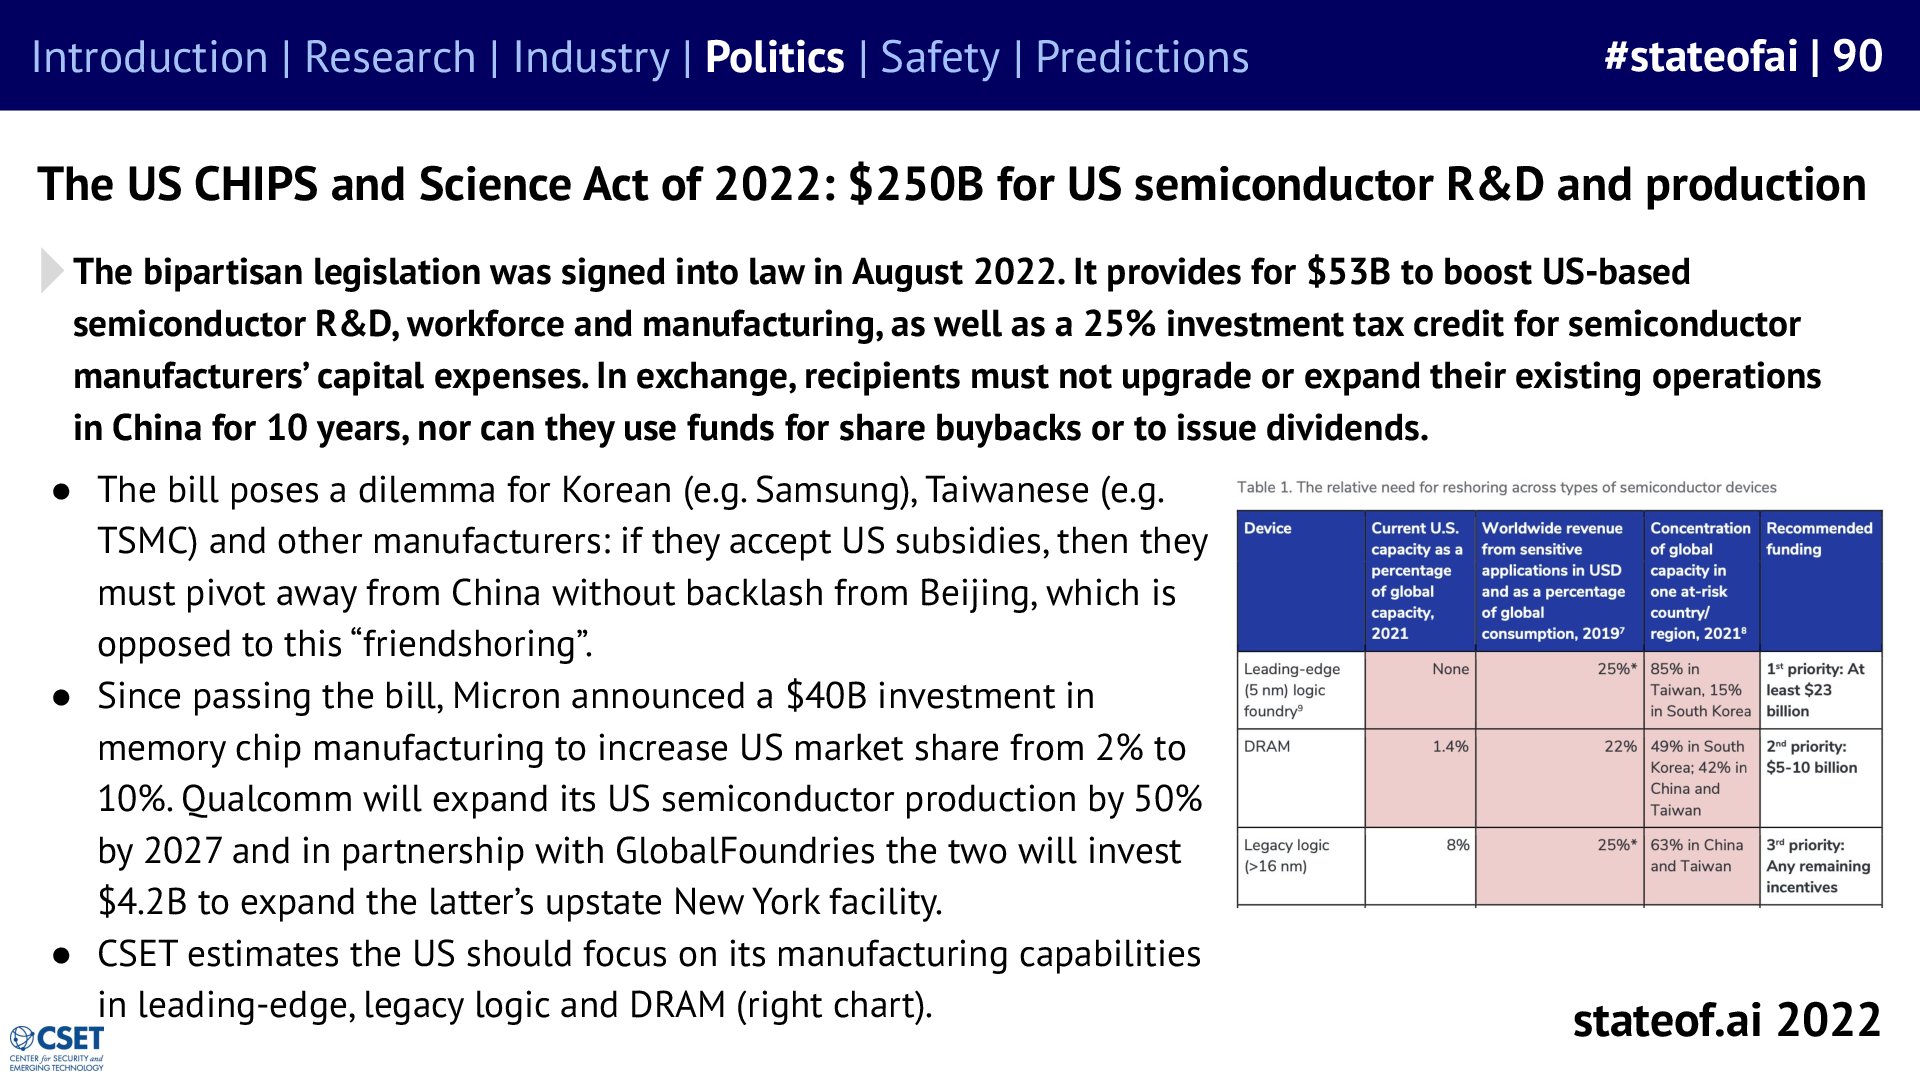
US legislation links subsidies with strategic conditions
The report described the August 2022 CHIPS and Science Act, including $53 billion for US semiconductor research, workforce, and manufacturing and a 25% investment tax credit. These were policy provisions, not a count of newly operating factories.
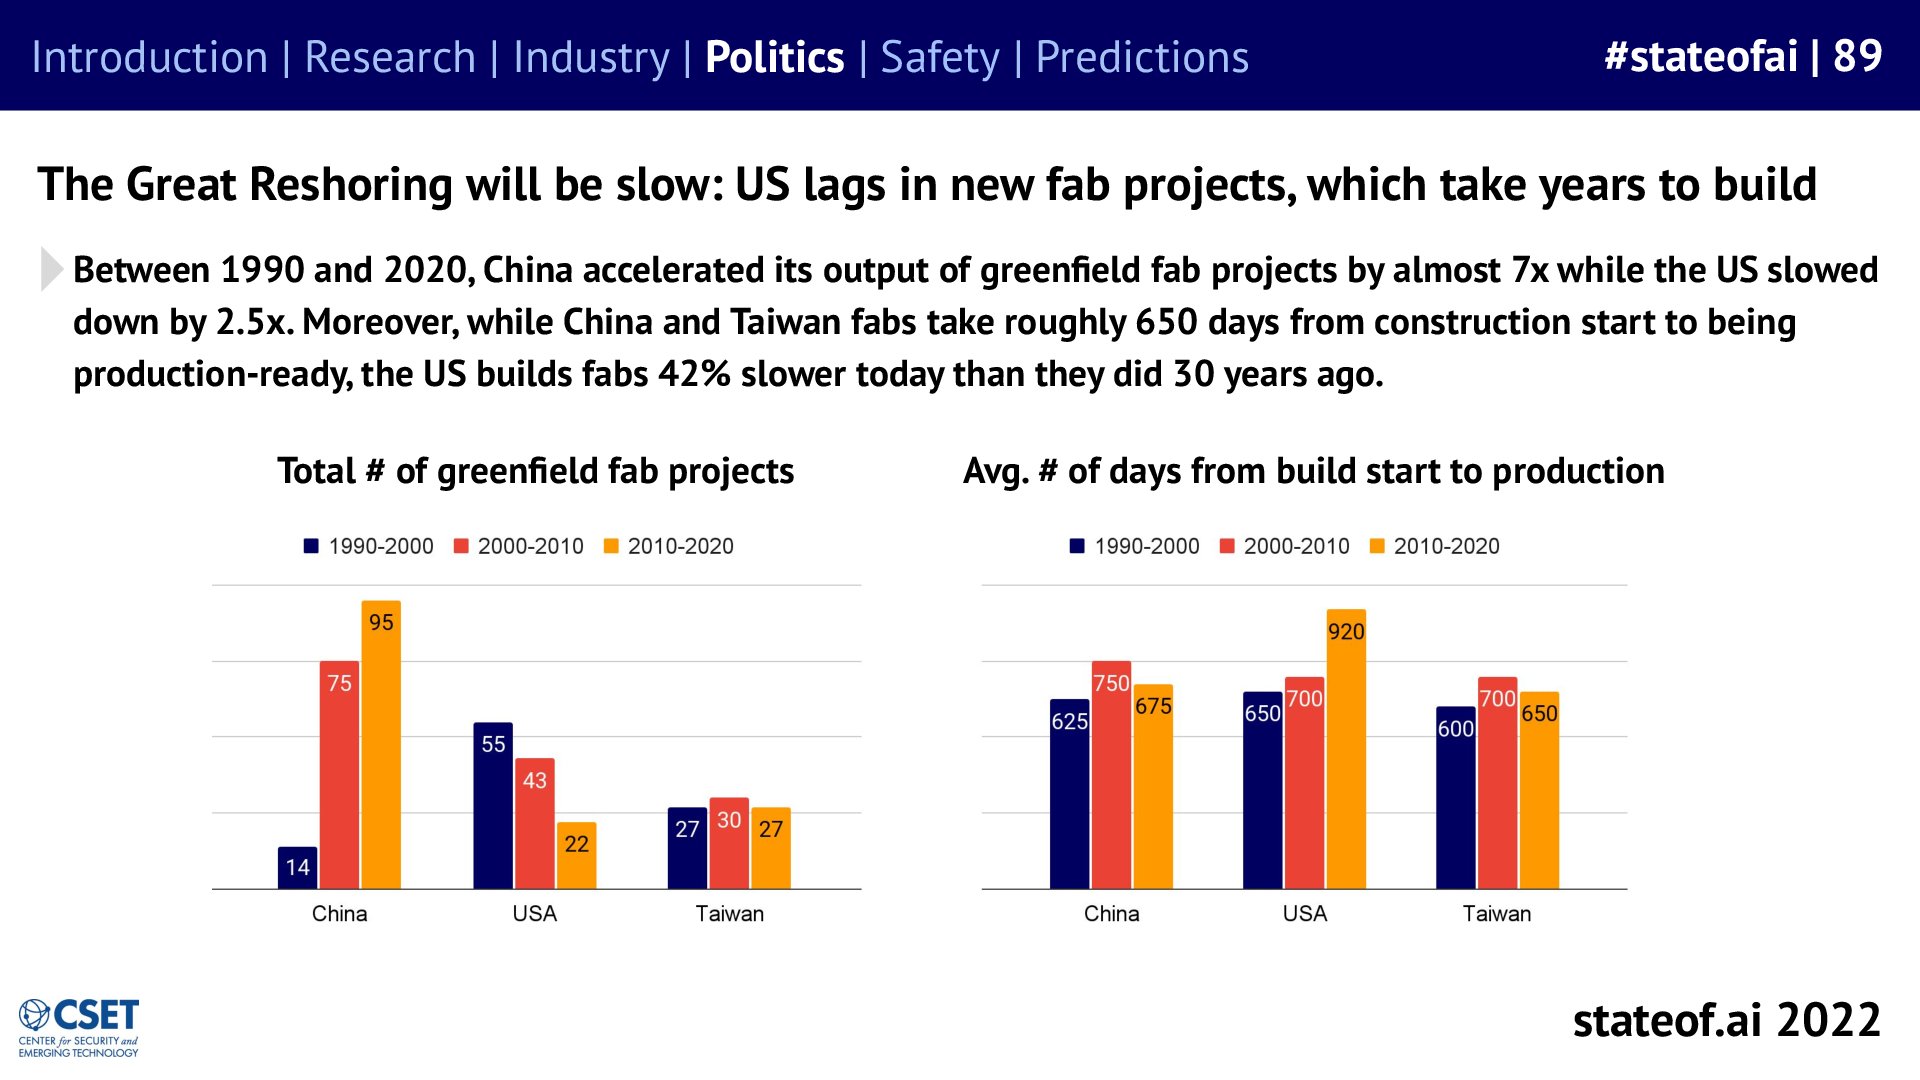
Manufacturing capacity cannot be switched on immediately
The report compared the time and activity involved in building semiconductor fabs across regions. It emphasized that construction and production-readiness took years, making rapid reshoring difficult even after governments committed substantial money.
Policy commitments had to pass through physical construction
Financial support could change incentives to build factories, but it could not instantly deliver their output. The report’s construction-time comparison put a practical timescale on reshoring ambitions. Readers should separate legislation, investment announcements, construction, and production when judging progress toward greater semiconductor capacity.
Evidence you can use
Politics in the 2022 report
Historical snapshot: October 2022. Dates and populations are specified per row.
This page preserves the October 2022 policy account and is not current legal or tax guidance. Authorized support, announced investment, construction, and operational capacity are different stages.
It described US support for semiconductor research, workforce, and manufacturing, including $53 billion and a 25% investment tax credit, as part of a strategic push to increase domestic capacity.
It referred to support for semiconductor research, workforce development, and manufacturing in the US legislation described. It was distinct from the broader headline size of the CHIPS and Science Act.
The report described an investment tax credit for semiconductor manufacturing capital expenditure. It should be read as the report’s historical account, not a current determination of any company’s eligibility.
Yes. The report stated that the legislation was signed in August 2022. Its discussion therefore concerned an enacted initiative, unlike the 2021 report’s treatment of the proposed EU AI Act.
It measured the time from construction start to production readiness for China and Taiwan in the cited historical comparison. It did not represent a universal construction guarantee.
The report described US construction as substantially slower than the China-Taiwan comparison. It used the gap to show why expanding domestic capacity required more than announcing funding.
No. Legislation and announced projects were steps toward capacity. Actual output depended on subsequent construction, equipment, staffing, and operation, which the funding figures alone did not measure.
Historical snapshot published October 11, 2022. This web edition was prepared on 2026-10-11 from the online deck and original launch posts. Findings and forecasts retain their original time frame.
Benaich, Nathan, and Ian Hogarth. “Semiconductors become an explicit industrial-policy priority.” State of AI Report 2022. Historical report snapshot; web edition prepared 2026-10-11.